Business Budgeting: How to Create an Effective Financial Plan — Review Copy
Business budgeting is an essential part of financial planning and management. A clear budget helps organizations understand how financial resources are expected to be generated and used during a specific period.
Without effective budgeting, businesses may struggle to control expenses, allocate resources, or prepare for unexpected financial changes.
What Is Business Budgeting?
Business budgeting is the process of estimating a company’s expected revenue, expenses, investments, and financial requirements over a defined period.
A business budget can cover a month, quarter, year, or another appropriate planning period.
It provides management with a financial framework for making decisions and monitoring performance.
Why Is Business Budgeting Important?
An effective budget can help organizations:
- Control operating expenses
- Allocate resources effectively
- Set financial targets
- Monitor business performance
- Identify potential financial problems
- Support strategic decisions
- Prepare for future investments
Budgeting also helps different departments understand the financial resources available to them.
1. Define Business Objectives
The budgeting process should begin with clear business objectives.
A company may want to increase revenue, expand into a new market, improve profitability, launch a product, or invest in technology.
Financial plans should support these objectives.
2. Estimate Revenue
Revenue projections should be realistic and based on relevant information.
Businesses can consider:
- Historical sales
- Customer demand
- Market conditions
- Pricing
- Seasonal trends
- Expected growth
Unrealistic revenue expectations can lead to inaccurate financial planning.
3. Identify Business Expenses
Businesses should identify all expected expenses.
These may include:
- Salaries
- Rent
- Marketing
- Technology
- Utilities
- Transportation
- Materials
- Professional services
Expenses can also be categorized into fixed and variable costs to make financial analysis easier.
4. Allocate Financial Resources
After estimating revenue and expenses, management can determine how financial resources should be allocated.
Resources should be connected to business priorities and expected outcomes.
5. Create a Contingency Reserve
Unexpected expenses can affect business operations.
Organizations can consider maintaining an appropriate financial reserve to help manage unexpected costs or temporary changes in revenue.
6. Compare Actual Results With the Budget
Creating a budget is only the beginning.
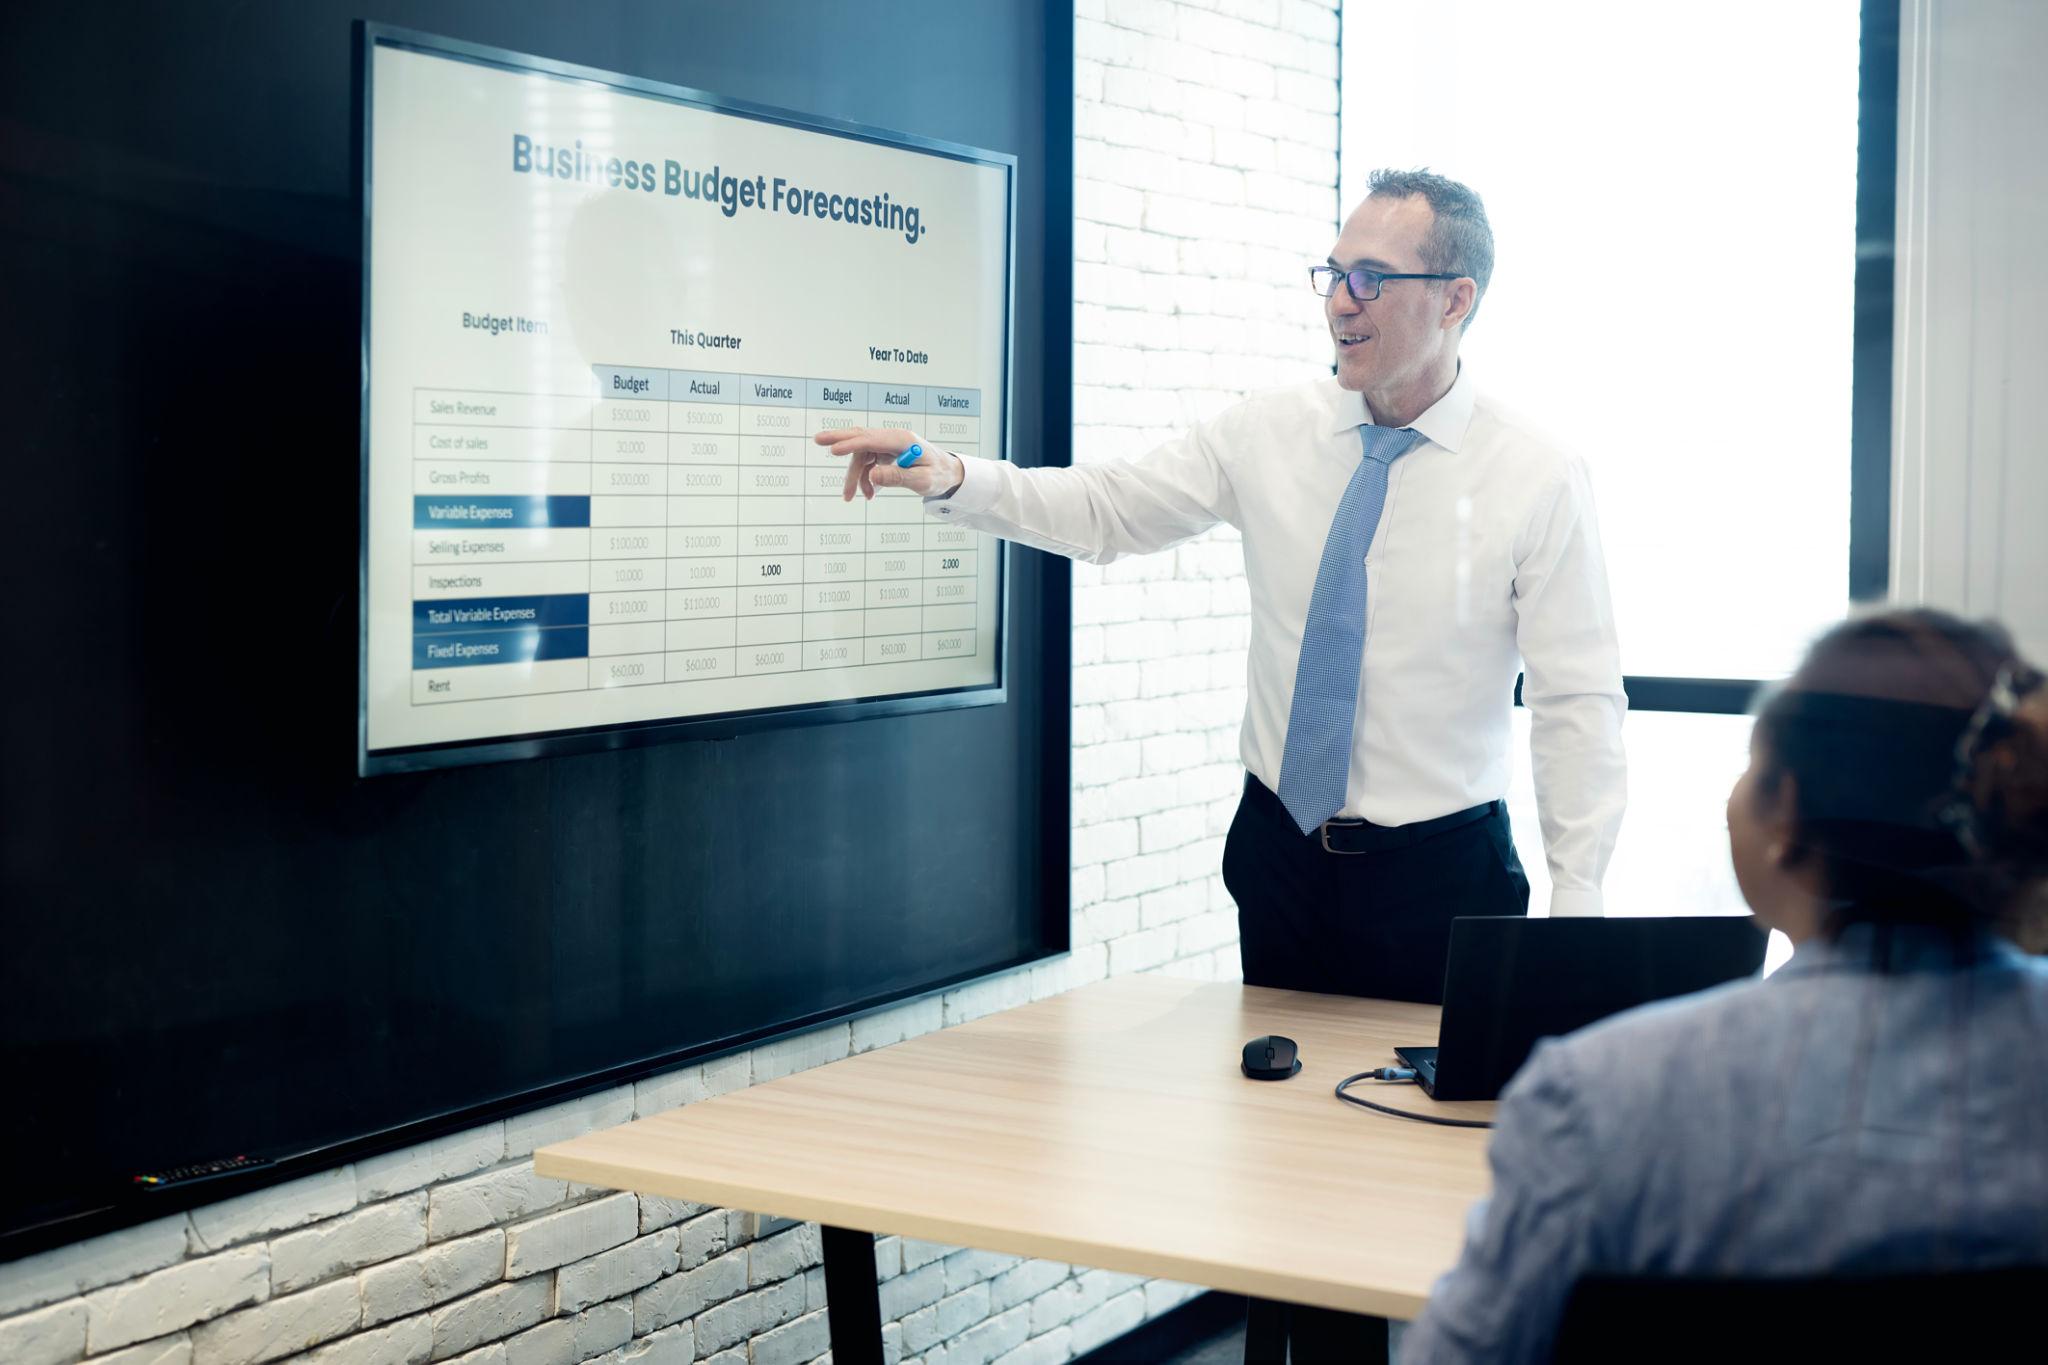
Organizations should regularly compare actual financial results with budgeted figures.
For example, if marketing expenses are significantly higher than expected, management can investigate the reason and determine whether corrective action is needed.
7. Update the Budget When Conditions Change
Business conditions are not always predictable.
Changes in customer demand, operating costs, market conditions, or strategic priorities may require organizations to revise their budgets.
An effective budget should therefore be treated as a management tool that can be reviewed and updated. Retain the original approved version and record the date, reason and approval for any revision. Present the latest forecast separately so readers can distinguish the original target from the current expectation.
Prepare a Minimum Budget Brief Before Collecting Numbers
The following checklist is a proposed management tool. It helps budget owners establish comparable inputs before consolidating departmental submissions; it is not a prescribed accounting standard.
| Input | What to record | Suggested owner |
|---|---|---|
| Scope and version | Entity, period, currency, cost centres and approval status | Finance coordinator |
| Activity assumptions | Expected workload, volume and capacity constraints, with dated evidence | Operational lead |
| Revenue and costs | Source assumptions, fixed and variable behaviour, and responsible reviewers | Sales and cost-centre owners |
| Cash timing | Expected receipt and payment dates, distinguished from revenue and expense recognition | Finance or treasury owner |
| Review and approval | Open questions, decision owner, due date and approval record | Budget sponsor |
Hypothetical example, not client data: an operations team expects additional orders but submits last year’s variable costs unchanged. Before approving the budget, the finance coordinator asks for the planned workload and cost assumptions to be reconciled. The review should test the assumption rather than simply accept a copied total.
When reviewing performance, distinguish a budget prepared for the original workload from an allowance adjusted to actual activity. ACCA’s budgeting guidance explains that distinction. Keep the chosen comparison visible in the report.
Connect the Budget to Learning and Operational Decisions
For the broader management process, read our financial planning and analysis overview. Professionals can also review the published FMVA course outline, which includes budgeting, forecasting and variance analysis, and confirm current details with the training team.
For team development, use HPA’s corporate training enquiry page to share participant roles, group size, current budgeting challenges and intended learning outcomes. Use anonymised examples and agree the scope before sharing confidential records.
Conclusion
Business budgeting provides organizations with a structured approach to financial planning.
By setting realistic revenue expectations, controlling expenses, allocating resources, monitoring financial performance, and adapting plans when conditions change, businesses can improve financial visibility and support better decision-making.

You may also like
Budget Variance Analysis: Explain Volume, Cost and Timing
Financial Planning and Analysis: How Businesses Can Make Better Decisions